
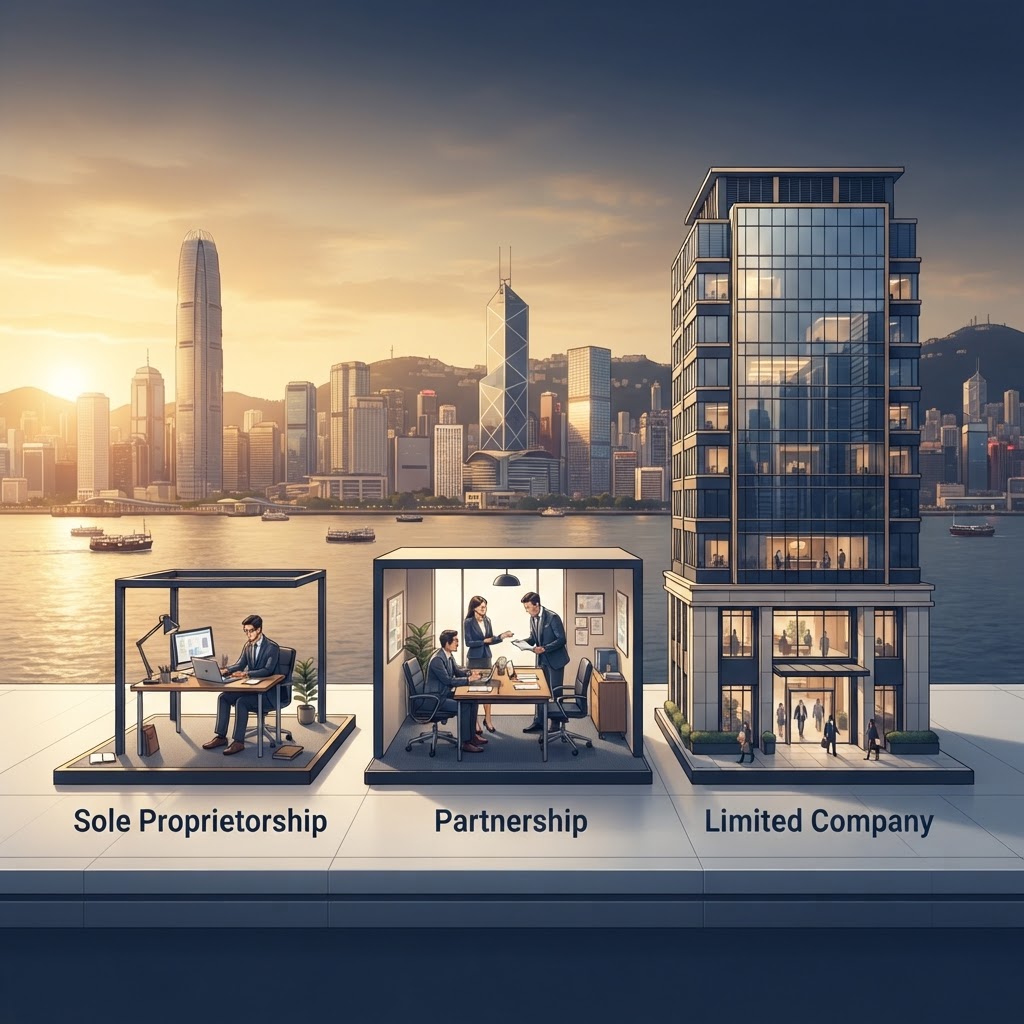
Hong Kong Business Structure Comparison 2026: Sole Proprietorship vs Partnership vs Limited Company
Hong Kong Business Structure Comparison 2026: Sole Proprietorship vs Partnership vs Limited Company
According to the Companies Registry, over 1.4 million companies are registered in Hong Kong as of 2025, with approximately 50,000 new incorporations each year. Yet many entrepreneurs still ask the same fundamental question before starting: sole proprietorship, partnership, or limited company — which structure is right for my business?
This guide provides a comprehensive comparison of the three primary business structures available in Hong Kong, covering legal liability, taxation, compliance costs, and setup requirements. Whether you are a freelancer, a startup founder, or a mainland entrepreneur expanding into Hong Kong, you will learn exactly how to choose the structure that minimises personal risk while maximising tax efficiency.
Quick Summary: Sole proprietorship is cheapest but has unlimited personal liability. Partnership shares risk but still exposes personal assets. A private limited company (Ltd) provides limited liability and the lowest tax rate (8.25% on first HK$2M profits) but requires annual audits and a company secretary.
1. Sole Proprietorship: The Simplest but Riskiest Option
What Is a Sole Proprietorship?
A sole proprietorship is a business owned and operated by one individual. Under the Business Registration Ordinance (Cap. 310), you must register with the Inland Revenue Department's Business Registration Office and obtain a Business Registration Certificate (BR). The owner and the business are legally the same entity — there is no separation between personal and business assets.
Key Features
- Registration fee: HK$2,200/year (one-year BR) or HK$5,720 (three-year BR)
- Taxation: Profits tax at 15% flat (unincorporated business rate, Cap. 112). No two-tiered rate benefit.
- Liability: Unlimited personal liability. Creditors can pursue personal assets.
- Compliance: Minimal — annual BR renewal and tax return. No audit, no company secretary.
A sole proprietorship suits very small, low-risk businesses — freelance designers, consultants, tutors — whose annual revenue stays below HK$2 million and who carry minimal debt. If your work involves significant client contracts or potential litigation, the unlimited liability makes this structure dangerous.
2. Partnership: Shared Risk, Shared Liability
What Is a Partnership?
A partnership is a business owned by two or more individuals (minimum 2, maximum 20 under the Partnership Ordinance, Cap. 38). There are two types: general partnership where all partners have unlimited liability, and limited partnership where at least one general partner has unlimited liability and limited partners enjoy protection up to their capital contribution.
Key Features
- Registration fee: HK$2,200/year (same as sole proprietorship)
- Taxation: Profits tax at 15% flat. The partnership itself is not taxed; each partner is assessed individually on their share of profits.
- Liability: In a general partnership, each partner bears joint and several unlimited liability for all partnership debts. A creditor can pursue one partner for the entire debt, even if caused by another partner.
- Compliance: Annual BR renewal, annual tax return, proper accounting records. No statutory audit required.
Partnerships are common among professional service firms — law firms, accounting practices, medical clinics. The joint and several liability rule makes partnerships risky for businesses with significant debt exposure. Always execute a detailed partnership agreement before commencing operations.
Expert Insight: According to the Hong Kong Bar Association, disputes between partners without a written agreement are among the most common commercial litigation triggers. A partnership agreement should cover capital contributions, profit-sharing, admission of new partners, withdrawal, and dissolution.
3. Private Limited Company: The Gold Standard
What Is a Limited Company?
A private limited company is a separate legal entity incorporated under the Companies Ordinance (Cap. 622). The company exists independently of its owners and managers. This separation is the foundation of limited liability protection — shareholders' personal assets are generally shielded from the company's debts, with liability limited to their unpaid share capital.
Over 95% of registered companies in Hong Kong are private limited companies, making it by far the most popular structure for serious entrepreneurs.
Key Features
- Registration fee: HK$404 (e-Registry) or HK$1,970 (hard copy). Plus BR fee HK$2,200.
- Taxation: Profits tax at 8.25% on first HK$2M, 16.5% above (Cap. 112, as amended 2018). Lowest corporate tax rate among major developed economies.
- Liability: Limited liability. Shareholders' exposure capped at nominal share value. Personal assets protected.
- Compliance: Annual return (NAR1), audit by HK CPA, company secretary (Cap. 622, s. 459–460), registered office, Significant Controllers Register (Part 5A).
- Perpetual succession: Company continues regardless of changes in shareholders or directors.
Annual Compliance Cost Estimate
| Item | Estimated Cost (HK$) |
|---|---|
| BR renewal | 2,200 |
| NAR1 filing | 105 |
| Company secretary | 3,000–10,000 |
| Registered address | 3,000–8,000 |
| Statutory audit | 8,000–25,000+ |
| Total | 16,000–45,000+ |
Note: Audit costs vary based on transaction volume. Figures are indicative for a small SME.
4. Side-by-Side Comparison
| Feature | Sole Proprietorship | Partnership | Limited Company |
|---|---|---|---|
| Legal entity | Not separate | Not separate | Separate entity |
| Liability | Unlimited personal | Joint & several unlimited | Limited to share capital |
| Tax rate | 15% flat | 15% flat | 8.25%/16.5% |
| Audit required | No | No | Yes (HK CPA) |
| Company secretary | Not required | Not required | Mandatory |
| Perpetual succession | No | No | Yes |
5. Real-World Scenarios
Scenario A: Freelance Graphic Designer (Revenue ~HK$500K)
A sole designer with no employees, minimal contracts, and no physical premises can operate as a sole proprietor. No audit or secretary costs save HK$10,000–20,000 annually. However, if client work involves significant deliverables, consider a limited company for liability protection.
Scenario B: Two Co-Founders Launching a Tech Startup (Target HK$5M+)
A limited company is essential. The two-tiered tax rate saves HK$135,000 in tax on HK$2M profits compared to the 15% unincorporated rate. The structure enables share-based vesting and future fundraising.
Scenario C: Two Doctors Opening a Clinic
A partnership may work if both carry professional indemnity insurance. However, many medical professionals now incorporate as a limited company to cap personal liability beyond malpractice insurance coverage — critical in an era of increasing patient litigation.
6. Can You Switch Structures Later?
Yes, but it's complex. Converting a sole proprietorship to a limited company requires incorporating a new entity and transferring all assets, contracts, and licences — a 2–4 week process that may trigger stamp duty on property transfers. Converting a partnership is even more complex, requiring unanimous partner consent and contract renegotiation.
This is why choosing the right structure from the outset matters. If in doubt, start with a limited company — the marginal compliance cost is small compared to the disruption of restructuring later.
7. Key Takeaways
- Sole proprietorship: Only for solo operators with very low risk and revenue under HK$2M. Unlimited personal liability is a serious drawback.
- Partnership: For professional firms with trusted partners. Always execute a detailed partnership agreement.
- Limited company: For any business with growth ambitions, significant contracts, or plans to raise capital. Two-tiered tax rate and limited liability make it the default choice.
- Tax efficiency: A limited company earning HK$2M profits pays HK$165,000 tax. A sole proprietorship pays HK$300,000 — a HK$135,000 difference.
- If in doubt, start as a limited company. The additional HK$16,000–45,000/year compliance cost is a small price for asset protection.
Need Help Setting Up Your Business Structure?
vOffice is a Hong Kong licensed TCSP (Trust or Company Service Provider) with over 23 years of experience in company registration, corporate secretarial services, and business compliance. Our team can help you incorporate a private limited company in 1–3 business days, act as your appointed company secretary under Cap. 622, provide a registered business address in Central, and handle annual compliance filings, audits, and tax returns.
Contact us today at voffice.com.hk/contact-us or chat with our AI assistant for instant guidance on your business structure.
References
- Companies Registry, HKSAR Government. "Companies Registry Statistics." cr.gov.hk. Accessed 2025.
- Companies Ordinance (Cap. 622). Hong Kong e-Legislation. elegislation.gov.hk. Key sections: s. 459–460 (company secretary), Part 5A (SCR).
- Inland Revenue Ordinance (Cap. 112). Hong Kong e-Legislation. Two-tiered profits tax rate: s. 14 and Schedule 3A; unincorporated rate: 15%.
- Business Registration Ordinance (Cap. 310). Hong Kong e-Legislation. BR registration requirements and fees.
- Partnership Ordinance (Cap. 38). Hong Kong e-Legislation. General and limited partnership provisions.
- Inland Revenue Department. "Profits Tax — Two-Tiered Profits Tax Rates Regime." ird.gov.hk.
- Companies Registry. "e-Registry." cr.gov.hk/e-registry. Incorporation fee: HK$404 (electronic).
- Hong Kong Bar Association. Guidelines on Partnership Disputes. Hong Kong Bar Association Publications.
About vOffice
vOffice is a Hong Kong licensed Trust or Company Service Provider (TCSP) with over 23 years of experience in company registration, corporate secretarial services, and business compliance. Located in Central, Hong Kong. Learn more at voffice.com.hk.
Related Articles
2026年香港中小企业政府资助完全指南:BUD专项基金新规、申请流程与避坑实务
科技券结束、市场推广基金并入、资助比例降至25%——2026年香港中小企业政府资助版图大洗牌。一文讲清BUD专项基金760万上限、申請易新规、申请资格、流程与53%申请被拒的避坑实务。
2026年香港僱傭合約完全指南:《僱傭條例》新修訂、「468制」連續性合約與僱主合規實務
2026年1月18日起香港連續性僱傭合約改行「468制」,法定假期增至15天,最低工資5月起上調至HK$43.10。本文以《僱傭條例》第57章為本,逐一拆解僱傭合約必備條款、通知期、遣散費計算與僱主合規清單,附官方參考來源。
2026年香港商業租約印花稅完全指南:稅率計算、30天法定期限、罰則與服務式辦公室豁免真相
香港商業租約印花稅(厘印費)2026全解析:《印花稅條例》第117章四級稅率0.25%–1%、30天打厘印期限、最高6倍罰則、第15條證據失效風險,以及服務式辦公室特許權協議毋須繳稅的關鍵分別,附稅務局官方計算實例。